Wednesday, 28 October 2015

My choice of the best Buy-To-Let deals on the market this week...


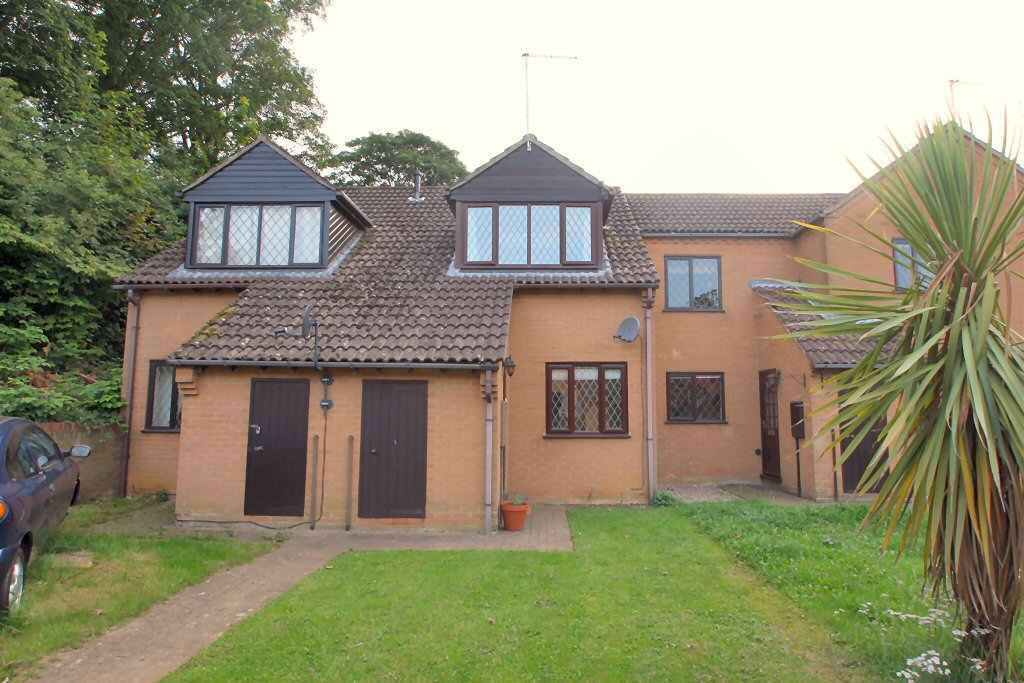
UNWIN ROAD, South Witham - PRICE £85,500
UPP Property Agents Tel: 01572 725 825
Two bed mid terrace close to centre of South Witham village with good connections. 
 
A cracking yield on this one, with an approximate rental of £450pcm.
http://www.rightmove.co.uk/property-for-sale/property-37043265.html

2 Bedrooms
Mid-terraced home
Re-fitted kitchen
Re-fitted bathroom
Gas central heating
Double glazing
Front garden


SISKIN ROAD, Uppingham - PRICE £136,500
UPP Property Agents Tel: 01572 725 825
Two bed coach house located within walking distance of the town centre.  Allocated parking and close to main road links.

Rental amount of approximately £450pcm.


2 double bedrooms
Coach house style apartment
Off road parking
Large living room
Bathroom with shower
Gas central heating


RYHALL ROAD, Stamford - PRICE OIEO £185,000
Murrays Estate Agents
Three bed terrace located close to local amenities and within a short walk to the centre of Stamford, complete with OSP.

3 bedrooms
2 reception rooms
Re-fitted kitchen and bathroom
Garden
Off-road parking
Gas central heating

Rental amount approximately £625pcm


Monday, 26 October 2015

Rutland and Stamford house owners desert the housing market with an 8 year low


Even though the housing market is in an upbeat state in many parts of the UK, getting on the property ladder is still challenging for many & regarded as ‘unattainable’ by some. However, that goal has become even worse recently in Rutland & Stamford as the number of houses available to buy is at an 8 year all-time low.

Back in spring 2008, there were over 776 properties for sale in Rutland & Stamford, and since then this has steadily declined year on year, so now there are only 233 for sale in these areas. This continuing diminishing supply of housing has been happening over those years for a while & there simply aren’t enough properties around here to match demand.

According to a recent report by the National Association of Estate Agents, that said, “There are now 11 house hunters fighting after every available house which isn’t sustainable.”   What that means is Rutland & Stamford youngsters, who are looking to buy their first home, are finding themselves being squeezed out by the competition.

However, in the meantime, nobody wants to live with parents until they are in their 30’s, so that in turn creates demand for more rental properties, which means landlords have a greater demand for more rental properties so are buying more, resulting in even less smaller properties for the youngsters to buy, it’s a vicious circle.   

Talking to fellow agents, mortgage arrangers, surveyors & solicitors in the towns, all of whom have extensive dealings in the Rutland & Stamford property market like myself, most of us agree the movement in our marketplace is taking place in the middle to upper market, higher up the property ladder and it’s ‘second and third steppers’ pushing through the properties that are being bought & sold.

That has meant as people tend to move less in the middle to upper market, the number of the properties actually selling has drastically reduced over the last couple of years.

When we look at some of the individual areas of the towns, it paints an interesting picture.

  • PE9 - Stamford, Ashton, Aunby, Bainton, Barholm, Barnack, Braceborough, Careby, Carlby, Collyweston, Duddington, Essendine, Easton-on-the-Hill, Great Casterton, Greatford, Ketton, Little Casterton, Newstead, Pickworth, Pilsgate, Ryhall, Southorpe, Tallington, Tickencote, Tinwell, Tixover, Uffington, Ufford, Wilsthorpe, Wothorpe 62 properties sold in May 2015 (with an average value of £238,132), whilst over the Autumn months of 2014, the number of properties selling in this postcode reached into the 70’s.
  • LE15 - Oakham, Cold Overton, Empingham, Knossington, Langham, Manton, Owston & Newbold, Thistleton, Uppingham, Whissendine 52 properties sold in May 2015 (with an average value of £251,720), whilst over the Summer months of 2014, the number of properties selling in this postcode reached into the 80’s.

So what does this all mean for our local homeowners and landlords?  Demand property in our area is good, especially at the lower end of the market.  But, with fewer properties coming up for sale, it means property prices are proving reasonably stable too.

I believe a more stable, consistent property market, with less people seeing property as an easy way to make a quick buck (as many did in the early 2000’s when prices were rising at nearly 20% a year so people were buying & selling every other minute), but a local property market that has a steady growth of property values, year on year, without the massive peaks & troughs we saw in the late 1980’s & mid/late 2000’s might just be the thing that Rutland & Stamford needs in the long term.

For more insights, comments & facts on our local property market please visit the Rutland and Stamford Property Blog www.rutlandandstamfordpropertyblog.co.uk where you will find many similar articles to this.
 

Friday, 16 October 2015

Oakham tenants feel the squeeze as rents continue to rise


As my regular readers know, my passion is talking about Oakham property. As a property agent I like to comment on the Oakham property market, which I hope will be of interest to both homeowners and buy-to-let landlords alike.

However, this week, I want to highlight the plight of the tenants of Oakham as bit by bit their wages are being taken up by ever increasing rents.  The cost of renting a home in Oakham has broken through the £700 a month barrier as the average rent for a property in the town, now stands at £710 per month, a rise of 1.6 % last month, leaving rents for new lets 6.6% higher than they were 12 months ago.

House price inflation has certainly eased in Oakham from the heady days of 2014, but still with retail price inflation (for goods and services) reducing to 0% any increase in property values, no matter how small, means in real terms property is still getting more expensive.

Meanwhile, many tenants have given up saving for a mortgage deposit, as rents continue to take a bigger slice of their wage packets, leaving nothing to save for a deposit. That means, progressively more tenants are deciding to rent for the long term and, therefore, the desire for decent high quality rental properties continues to exceed the available rental stock.

I would go as far as to suggest that rents are an ideal barometer to the state of the local economy as a whole and strongly believe that the recent increase in Oakham rents are a sign that the Oakham economy is picking up. 

This means Oakham landlords are continuing to capitalise on the Oakham property market. The most recent Land Registry data suggests the annual property price rises in the town have eased over 2015, leaving property values only 4.85% higher than 12 months ago, so as property price growth is easing off, with the increased rents, rental yields are strengthening for the first time in years to compensate.

The mortgage market has become more stable after the mad months of May and June after the Tory’s got back into No.10, and so, everything is set to be good news for landlords; even with the Chancellor’s change of tax rules in the coming years for buy-to-let mortgages.  You can get some amazingly low mortgage rate deals at the moment, so with mortgage rates so low and returns still extraordinarily attractive, there’s rarely been a better time to invest in rental properties.

However, (you knew there would be a ‘however’!), it’s all about buying the right property at the right price. Not all property types are seeing equal rises in rents and capital growth.  Different parts of the town and different types of properties are experiencing quite different changes.

For example, the average length of time the 7 Oakham properties up for rent between £250 to £500 per month is 26 days, whilst the average length of time the 21 properties at £500 to £1000 per month is 30 days and 7 properties that fall into the £1000 to £2000 per month price bracket is 26 days. When you start comparing different parts of Oakham, the numbers are even stranger!  The bottom line is that you must take advice and opinion.

To discuss any potential buy-to-let properties currently on the market that have caught my eye, or if you have your own property to discuss, please contact me to arrange a suitable time for us to meet.  
I look forward to hearing from you.
Email me: David@upp-property.co.uk  or call me on 01572 725 825 / 01780 484 554

Friday, 9 October 2015

Could your Stamford property save you from PENSION OBLIVION?


If you were born in the early 1970’s or late 1960’s, and if you haven’t started to think about it yet, retirement is closer than you think. In fact, the number of years you have left to work is less than the number of years you have worked. The basic state pension is worth £115.95 a week for a single person in 2015/16 (or £6,029 a year) and £231.90 a week for a couple (£12,118 a year) as long as your partner has paid their ‘stamp’ or as we now call it ‘National Insurance’ (although there are certain ‘get out of jail’ cards if they haven’t). 
As a household, could you live on just over £12k a year?

However, could the Stamford property you are living in save you from retirement poverty?  You see, a regular retirement income is vital, and the bricks and mortar you own in Stamford could provide a way for you to finance life when you retire.

If you are in your 30’s, instead of saddling yourself with rising mortgages, going from your ‘first time buyer’ flat, to a terrace, to the semi and then the large detached house, you could instead keep your terrace or small semi, turning it into buy a buy- to-let property, let the rent pay the mortgage and then rely on capital growth to provide you with a lump sum when you sell the property and retire.  One of the biggest plus points of buy-to-let is what is known as leverage. Let me explain ... say you have a deposit of 25% and the value of the property rises by 3% a year, your gains in fact multiply to 12%.  However, if property prices drop, 'leverage' can be catastrophic, as losses will also be multiplied. Property values have dropped a number of times in the last 50 years, but they always seem to bounce back ... property must be seen as a long term investment.

Let me explain how leverage could work for you. If you had bought a Stamford house in the spring of 1983 for £35,000, using a 75% mortgage and 25% deposit, (meaning your deposit would be £8,750). Today, that Stamford property would have risen in value to £224,641, a rise of 541.8%. However, when you look at the growth on just your deposit, the rise is even better ... instead of 541.8%, we see a rise of 2467% (remembering that the mortgage would have been paid off).

However, buy-to-let is not all about capital growth.  In retirement, income is more important than capital growth, as monthly rent is the key to a steady income.

So surely the best strategy is to buy those Stamford properties with the high rents (when compared to the value of the property). These are called high yield properties in the buy-to-let world because the monthly return is so much greater. So surely they are the best in Stamford? Possibly, but the properties that offer these higher yields (in the order of 6% to 9% per year) tend to be in places such as the Essex Road area in Stamford.  Historically they haven’t offered such good capital growth when compared to the town average, have a higher tendency for void periods and such properties tend to attract tenants that have a greater propensity to be high maintenance.

Therefore, if a high maintenance rental portfolio wasn’t for you, another strategy could be buy a property with relatively smaller rental returns of 4% to 5% per year (i.e. lower yields), but in a more up-market area such as Tinwell Road / Roman Bank area. Properties such as these tend to suffer from less void periods (i.e. when there is no tenant in the property paying you rent) and they historically have had better long term capital growth when compared to the town average.

Every landlord is different and every property is different. All I suggest to you is do your homework.

As regular readers will know, I am happy to share my knowledge and experience of the Stamford property market; high yields, high capital growth, what to buy, what not to buy and where to buy in the Stamford Property market.

Please contact me via david@upp-property.co.uk or call me on 01780 484 554, and I will be happy to chat it all through with you.

Tuesday, 6 October 2015

This week's B2L deals...


Here are 3 more B2L properties on the market this week that look very interesting.  All very different in their offering, and indeed their price, but there are tenants out there for all 3 genres of property. 

1) King Edwards Way, Edith Weston-  £385,000 (UPP Property Agents)

http://www.rightmove.co.uk/property-for-sale/property-36057582.html  

Currently let at £1,200pcm

Detached 3 bedroom cottage, close to Rutland Water.

Spacious family accommodation with no upwards chain.

This would make a cracking investment especially with the long term in mind as it would add capital value, give you the option to extend (stlpp) and would be a great family home should you want it back in a few years to live in yourself.

  • Detached Cottage

  • Three Bedrooms

  • Three Bath/Shower Rooms

  • Large Living Room

  • Spacious Kitchen/Breakfast Room

  •  


    Contact Adrian McCarthy, UPP Property Agents
    Tel:      01572 725 825
    Email: Adrian.mccarthy@upp-property.co.uk


    2) Hectors Way, Oakham - offers over £189,995 (Moores Estate Agents)
    End terraced 3 bedroom town house style property, garage, garden, gas central heating.

    A wonderful rental investment.  We manage a number of similar properties on the same development; they are always sought after by young families wanting a long term let and achieve £695pcm


    3) Tods Terrace, Uppingham - £129,950 (Gilbert & Thomas)
    Mid terraced 2 double bedroom home with garden and outbuilding.

    Literally a minutes walk from Uppingham town centre. Income c£500 - £525pcm, perfect for the young professional.

    http://www.rightmove.co.uk/property-for-sale/property-52725926.html

    Or if you're interested in purchasing a different property in Rutland and Stamford, and would like my opinion on it, and a realistic rental valuation, please contact me on 01780 484 554 or email me: david@upp-property.co.uk

    Friday, 2 October 2015

    Langham Residents can thank the school for an average £6,400 windfall


    I was having a chat with an Oakham property investor the other day, when he asked if schools, especially primary schools, affected the local property market in terms of demand from buyers and tenants to a property.

    Anecdotally, I have always known this to be true, a good school creates good demand and good demand does affect house prices.


    So, I asked my colleagues on the front line, who take the phone calls from people putting themselves on our mailing list and they confirmed that most people cite location as their number one factor.
    After looking through our mailing list, it confirms there is a close correlation between the high demand areas of Oakham and the close proximity to a good primary school. Talking to my team in a recent morning meeting, they agreed many people would look to increase their budget quite significantly, whilst others would consider downgrading their property requirements to be close to a good primary school.

    Those of you who regularly read this blog will know I like a challenge, so I decided to look at the science behind these assumptions. According to the SchoolGuide website, Langham Primary School is one of the best primary schools in Rutland. Its figures are certainly impressive. Their last Ofsted Report classified it as Outstanding, 72% of 11 year pupils achieving Level 4 or above in maths, reading and writing whilst 31% of them achieved level 5. There is also an excellent pupil/teacher ratio of 24:1. Finally, the schools’ KS2 rating was classed as good.
    Looking at property sales within the catchment area of the school, property values have risen in value since 2002 by 35.2% whilst according the Land Registry, the Oakham average as a whole has risen in the same time frame by 33.4%.

    That doesn’t sound a lot of difference, but when you apply that difference to the value of an average property in Langham, those extra few percentage points make over £6,400 difference in property price growth in Langham, when compared to the Rutland County average ... interesting, don’t you think?

    However, whilst a good primary school significantly contributes more to house prices, the same can’t be said for secondary school. There are two reasons for this, firstly, as secondary schools are much larger, so their catchment areas are correspondingly much larger, meaning parents don’t need to live so close to the school. Secondly, in the UK, whilst the difference between the top 25% and bottom 25% of secondary schools is not insignificant, in the primary school sector, the difference between the top 25% and bottom 25% is, according to the London School of Economics, is considerably and significantly more.

    Many other Oakham landlords, both who are with us and many who are with other  Oakham agents, like to pop in for a coffee or ring/email us to  discuss the Oakham property market, to consider how Oakham compares with its closest rivals and hopefully we can answer all their questions. You must take lots of advice and seek out the best opinion. 

    If you have any questions, please contact me and I will be glad to offer you my honest, straight talking opinion.  I don't bite and I don't hard sell.

    Email: david@upp-property.co.uk or call me on 01572 725 825


    Friday, 25 September 2015

    George Osborne – The Oakham landlords’ friend?

    Well, the last few weeks has been rather hectic as Oakham landlords, some who use us to manage their properties and other landlords who just read our Oakham Property Blog, have been sending me emails or picking up the phone to ask me about the new rules on buy-to-let taxation announced in the recent budget. George Osborne confirmed in the recent summer budget that the tax relief given to landlords on mortgage interest payments, on their buy-to-let (B2L) properties, would be reduced over the coming years for higher rate income tax payers. The Chancellor said the tax relief for private buy-to-let landlords (who pay the higher rate of income tax) would change in 2017 from the current 45% / 40% and would steadily reduce over the following 4 years to the existing 20% by 2020.

    With 14.1% of residential property in the Parish of Oakham being privately rented (as there are 659 privately rented properties in the town), these changes are potentially something that will not only affect most Oakham landlords, but also the tenants and the wider property market as a whole. The choice of rental properties could drop, especially at the top end of the market which could push up rents.

    However, Oakham landlords could protect themselves by reassigning 1 or more rental properties into a company structure (e.g., a Limited Company, Partnership or Sole Trader) and by doing so, the total tax paid is greatly reduced, because a company only pays tax on the profit. Nonetheless, before everyone goes off setting up companies for their B2L portfolios, it must also be noted, if a sole trader firm is started, stamp duty needs to be paid, yet if the owner is in business with a partner, they could enjoy some stamp duty relief.  The biggest tax variation is Capital Gains Tax (CGT) where the tax bill will be much higher when you come to sell your portfolio. In essence, by going into business with your B2L properties, you will potentially have a modest stamp duty to pay when you start, but you will have a lot less monthly tax to pay, irrespective of the interest rate, but the CGT bill will be much higher when you come to sell ... as you can see, it is not a ‘get out of jail card’. Now it must be remembered, I am not a tax advisor, so you must take advice from a qualified person.

    Those planning to purchase a B2L property will have to factor these new rules into their calculations, and this could affect the offers they are willing to make. However, I am not that concerned, as the scaremonger reports fail to see the fact that two out of three B2L properties that have been bought since 2007 have been purchased without the support of B2L mortgage. With those two thirds of landlords paying cash for the purchase of their rental properties, that means two thirds of landlords will be totally unaffected by the changes.

    So what of the future? The British love their 'Bricks and Mortar', it’s an asset that they can touch and feel and has a 70 year track record of capital growth that has out-stripped inflation. Buy-to-let will still be attractive to Oakham investors and let me explain why. If you invested £30,000 in Oakham property in September 1987, today it would be worth £132,797. If you had invested the same £30,000 in to the London Stock Market (the FTSE 100 to be exact), it would be only be worth £85,879 today, whilst Inflation would have taken the original £30,000 and pushed it up to £62,345.

    It’s true some central London landlords relying solely on the tax breaks rather than high yields may be forced out of the market, but even those landlords could seek to recoup any losses by increasing rents. However, those landlords may leave the market and this could constrict the availability of rented houses even more than it is already, increasing rents and thus pushing yields even higher for landlords and B2L investors still in the market... thus attracting new landlords into the market because of those higher yields.

    The reality is, there is too much demand and not enough supply of homes for people to live in in the town. Official figures show the population in Oakham is rising by 94 persons per year (i.e., demand rising), but only 58 properties are being built each year (i.e., supply is low). This sets up the Oakham (and UK) property market to continue to create strong and steady returns, irrespective of any tax loophole being there (or not as the case maybe).

    To see the 3 interesting B2L properties currently for sale that I’ve got my eye on, please read my post from earlier this week.

    Thursday, 24 September 2015

    Latest B2L's I have my eye on...

    There are 3 properties I have my B2L eye on this week...

    1) Firstly, a great family house on Willougby Road in Stamford.  3 bedroom semi-detached.  Would be a great rental property for a young family looking to put down roots and some security for a few years, would achieve circa £695pcm.  On the market with Nest Estates for £185,000 - click on this link for its on-line property listing...
     
    2) Secondly, a charming 2 bedroom end terraced home on West Road in Oakham. On the market with Gilbert and Thomas for £160,000. It's close to the town centre, train station etc.,  and you could expect this property to receive in the region of £625pcm, and would be ideal for a young professional couple, divorcee or retiree.  Again, click on this link to see its full details:-
    http://www.rightmove.co.uk/property-for-sale/property-36281997.html

    3) And lastly, this property on Willow Close, Uppingham has been successfully 'tried and tested' as a great rental home for a number of years, now achieving £525pcm.  It is well maintained, already in good decorative order, situated close to the town centre and has the added benefit of a parking space and rear garden.  Everything a savvy landlord, or indeed a tenant, is after. 
     
    Brand new to the sales market, it is encouragingly priced at £137,500.  Remember, this property would achieve you a rental income of £525pcm. 

     
    For more details, please call:-
     
    Call Adrian McCarthy
     
     UPP Property Agents on 01572 725 825
     

    Thursday, 17 September 2015

    Stamford Landlords' mortgages top £83million!


    The Brits can’t stop talking about property. The hot topic of discussion at the dinner parties of Wothorpe, Barnack, Uffington and Great Casterton’s movers and shakers is the subject of the Stamford property market, but in particular, buy-to-let (B2L). These people are buying up buy-to-let properties quicker than an ace Monopoly player... or so it would seem if you read the Sunday papers. So is the buy-to-let market a sure fire way to make money?  Is it something everyone should be jumping into? Is it a sure fire way to make money? The answer is Yes and No to all those questions!
    Firstly, a landlord only has to flick through Rightmove or Zoopla, pick any property at random and agree a price. Then, find a modest deposit of 25% (often by remortgaging their own home) which, for an average Stamford terraced house, would mean finding £50,852 for the deposit (as the average Stamford terraced house is currently worth £203,409) and borrow the rest with a low interest rate buy-to-let mortgage.  Finally, the landlord would rent out the property in a matter of hours for top dollar and live happily ever after, with the rent then covering the mortgage payments, with loads of money to spare and come retirement have a portfolio of property that would have quadrupled in value in fifteen years. Sounds wonderful – doesn’t it? Or does it???

    Let us not forgot that the half of one per cent Bank of England base rate is artificially low. The international money markets can be fickle and if interest rates do rise quicker and higher than expected because of some unforeseen global economic situation, that monthly profit will soon turn into a loss as the mortgage will be more than the rent.

    Even though tenants are staying longer in their rental property, tenants still come and go and my guidance to landlords is they should allow for void periods, plus the maintenance costs of a rental property and of course, agents fees...all things that eat into that profit.

    Interestingly, by my calculations, there are approximately 448 Stamford landlords owing in excess of £83 million in mortgages on those Stamford buy-to-let properties.  An impressive amount when you consider Stamford only has 0.042% of all the rental properties in the country. It really does come down to a number of important factors going forward to ensure you are water tight for the future.

    A lot of my existing landlords are fixing their mortgage rates. One told me that the Metro Bank are currently offering a 5 year fixed B2L re-mortgage rate at 3.79% for 5 years (based on a 75% loan). I don’t give financial advice, so you must speak with a qualified mortgage advisor - but that sounds very fair!

    However, one thing I do know is that buy-to-let is a long term investment, it’s a ten, fifteen, twenty year plan and property prices will go down as well as up. You wouldn’t dream of investing in the stock market without advice, so why invest in the Stamford property market without advice? We give bespoke detailed advice to our landlords to enable them to spot trends in the Stamford property market before others, enabling them to buy better properties at better prices.

    For example, did you know that flats are selling for around 35% lower than 12 months ago in Stamford, yet detached properties are selling for 41% more (with every other type in between). This means we can advise on which properties will go up in value better (or lose less if property prices drop), we can also advise which have lower voids and which properties have higher maintenance issues.  

    Information on the local property market and ability to process it is the strongest asset we can give you.

    As Lois Horowitz, the famous author says, ”Not having the information you need when you need it leaves you wanting. Not knowing where to look for that information leaves you powerless. In a society where information is king, none of us can afford that”.

    If you are also considering purchasing a property for Buy-to-Let purposes, then why not run the property details past me?  I'd be happy to discuss it with you in confidence.

    Friday, 11 September 2015

    The "Liquorice Allsorts" Oakham property market


    Despite the UK economy heading in the right direction with record low mortgage rates and unemployment  figures dropping,  the rate of property prices rising in Oakham have tempered since the start of the year. This slow, but sure, downward trend in the rate of growth has been in evidence since mid-2014.  The increase in property values continue to outpace the growth in salaries.  However, the gap is closing, helped by a lift in salaries over the last 6 months.  Property values in the East Midlands region as a whole are 2.9% higher than a year ago.  Compare this to the neighbouring regions of the West Midlands at 3.5% higher and Yorkshire at 1.1%, the majority of the country continue to see annual house price gains - the exception being Wales which recorded a slight  decline of -0.6%.

    Even with the tempering in house price inflation, it does not necessarily change my outlook that property prices are likely to be firmer over the second half of 2015 amid heightening activity in the Oakham property market.  As stated in a previous article, there is a current shortage of properties on the market, restricting supply, which in turn will provide stability and support to Oakham property prices. Therefore, my overall opinion is that Oakham property prices will rise by 5% over 2015 and roughly the same in 2016.

    Property investment is a long term business.  Buying the right sort of property is vital. I have recently been speaking with a number of Oakham landlords about the importance of a balanced portfolio, when buying and renting out property. The balance between buying properties that offer good monthly returns (high yields) but quite often offer poor capital growth (i.e. they don't increase in value that much over the years compared with the average) versus properties that do go up in value quicker but often offer a lower yield.  So, what type of properties have performed best over the last few years in Oakham, especially in terms of their capital growth?

    When comparing what the average price of detached, semi-detached, terraced and flats were selling for back at the start of the Millennium to the present day, the results are quite remarkably different, almost like a bag of “Liquorice Allsorts”, as the different types of property have performed poles apart over the last 15 years:

    ·         Detached Houses in 2000 were selling on average for £107,115 and so far in 2015, they have been selling on average in Oakham for £320,707 a rise of 199%

    ·         Semi-Detached Houses in 2000 were selling on average for £62,328 and so far in 2015, they have been selling on average in Oakham for £176,488 a rise of 183%

    ·         Terraced Houses in 2000 were selling on average for £51,750 and so far in 2015, they have been selling on average in Oakham for £170,180 a rise of 229%

    ·         Flats and Apartments in 2000 were selling on average for £53,950 and so far in 2015, they have been selling on average in Oakham for £96,500 a rise of 79%

    Moving forward, what should new and existing buy-to-let landlords do with this information?  Well, the questions I seem to be asked on an almost daily basis by landlords are:

    ·         “Should I sell my property in Oakham?”

    ·         “Is the time right to buy another buy to let property in Oakham and if not Oakham, where?”

    ·         “Are there any property bargains out there in Oakham to be had?”

    Many other Oakham landlords, who are with both us and other Oakham letting agents, like to pop in for a coffee,  pick up the phone or email us to  discuss the Oakham property market, how Oakham compares with its closest rivals (Stamford, Melton Mowbray, Peterborough and Grantham), and hopefully answer the three questions above.

    I don’t bite, I don’t do hard sell, I will just give you my honest and straight talking opinion and look forward to hearing from you.

    Friday, 4 September 2015

    This week's BEST Buy-To-Let options...

    Firstly, let's look at the tidy 3 bed mid-terrace on Edinburgh Road, Stamford.  Currently on the market with Sowden Wallis with a guide price of £160,000

    • It's a good size with 3 bedrooms
    • Situated in a popular Stamford location, close to town and easy access for A1 commuters
    • Well presented throughout to maximise on your rental income.  No need to renovate first.
    • Sitting room with modern open plan kitchen / diner.  It's light and airy.
    • Bathroom with shower - a bit dated, but the shower is the important factor here.
    • Enclosed low maintenance rear garden.
    • Gas central heating.  uPVC double glazing.
    This will appeal to a broad spectrum of tenants such as young families, young professionals and retirees.

    Would achieve in the region of £595pcm - -£625pcm.


    My second (and much cheaper) option already has happy respectful tenants in place wishing to stay long term.  Currently on the market with UPP Property Agents, with a guide price of just £125,000.  Call Adrian McCarthy on 01572 725 825.

    It's well located on Queens Road, Uppingham.

    http://www.rightmove.co.uk/property-for-sale/property-36068631.html


    Very spacious, good proportioned home with 2 bedrooms.
    Immaculate order. Well presented and maintained. Happy tenants in place.  IMMEDIATE income. Win win!
    Great central town location.
    Bathroom a bit dated, but don't forget the tenants have made this their home and are keen to stay put.
    Fabulous, established rear garden.  Well stocked.  Huge appeal.
    Gas central heating.  uPVC double glazing.

    This little gem will be achieving you an instant rental income of £450pcm (and we understand they are due a rent increase soon too) from the date of completion.  They don't build 'em like this these days, do they?

    If you would like to discuss either of the above in more detail with me, in confidence, please contact me.   Alternatively, if  another Buy-to-Let property has caught your eye and you would like to chat it through, again, please call me.  I'd be delighted to talk to you about it.

    david@upp-property.co.uk /TEL:  01780 484 554


    Thursday, 27 August 2015

    Stamford home owners move every 11.9 years

    During my school years, my parents seemed to move every other year (or it seemed that way). In reality, looking back at the house moves, we actually moved 3 times before I left home. However, whilst my parents kept the removal van people in business whilst I was at school, from research I have carried out it shows things have changed considerably in Stamford over the last few decades, and interestingly, the trend is getting worse ... for the removal van people at any rate!

    In Stamford, there are 8,994 properties. However, after we remove the 1,399 council houses, 1,497 privately rented houses and 138 houses where the occupants live rent free, that leaves us with 5,960 owned properties (be that 100% outright, with a mortgage or shared ownership). This means 66.3% of the properties in Stamford are occupied by the owner (the national average is interestingly 64.2%) but the number of people who have sold and moved house in Stamford, over the last 12 months, has only been 500. This means on these figures, the homeowners of Stamford are only moving on average every 11.92 years.

    These are the reasons; Firstly, the cost of moving house has risen over the last 20 years. Secondly, with many remortgaging their properties in the mid 2000’s before the price crash of 2008, there is a reluctance or inability in a small minority of homeowners to finance a home sale/purchase, due to lack of equity. These are both factors driving fewer moves by existing homeowners.

    However, the big effect has been the change in house price inflation. Back in the 1970’s and 1980’s, house prices were doubling every 5 to 7 years. Even in Greater London, with its stratospheric property price increases over the last few years, it has taken 13 years (August 2002 to be exact) for property values to double to today’s levels.

    This change to a relatively low inflation Stamford property market (i.e. Stamford property values not rising quickly) is significant because the long term consequences of sustained low house price growth is that it eats into mortgage debt more slowly than when property price inflation is higher. Stamford homeowners cannot rely on inflation to shrink their debt in real terms as much as they did in say the 1970’s and 1980’s.


    So what does this all mean for Stamford buy to let landlords? Well for the same reasons existing Stamford homeowners aren’t moving, fewer ‘20 somethings’ are buying their 1st home as well. Stamford youngsters may aspire to own their own home, but without the social pressure from their peers and parents to buy their 1st property as soon people reach their early 20’s, the memory of the 2008 housing crisis and the belief the hard times either aren't over or the worst is yet to come, current and would-be homeowners are warming to the idea of renting. I also believe UK society has changed, with the youngsters wanting prosperity and happiness; but wanting it all now... instantly... today... without the sacrifice, work and patience that these things take. As a society, we expect things instantly, and if it doesn’t come easy, doesn’t come quick, some youngsters ask if it is really worth the effort to save for the deposit? Why go without holidays, the newest smart phone, socialising four times a week and the fancy satellite package for a couple of years, to save for that 5% deposit if there is no longer a social stigma in renting or pressure to buy as there was... say... a generation ago?
    Even though, in real terms, property prices are 5% cheaper than they were 10 years ago (when adjusted by inflation), 16.6% of Stamford properties are privately rented (nearly double it was 20 years ago). As a result, the demand for rental properties continues to grow from tenants, meaning those wishing to invest in the buy to let market, over the long term, might be on to a good thing.


    For advice and opinion on the Stamford Buy-To-Let property market, please visit our office on 12 St.John's Street, Stamford.

    Friday, 21 August 2015

    Are 'would be' Rutland homeowners warming to the idea of renting?

    I was reading a report the other day produced by the Halifax, about the UK property market & why of the younger generation seem to be renting rather than buying. I find it fascinating that over the last 10 years, the British obsession of buying a house almost as soon as you left school, & the fact that if you rented you were seen as a 2nd class citizen, has turned on its head to a point where the hopes & dreams to own a nice home will be replaced by the ambition simply to live in one.

    In the latter half of the 20th Century, you left school, got a job, bought a small house and kept buying and selling property, constantly upgrading, until eventually they carried you out in a box.  However, the perceived shame and stigma of renting is no longer the case, as it seems the British are now beginning to accept this flexible lifestyle.  This is a very important consideration for both Rutland homeowners and Rutland landlords, as it will transform the way the Rutland property ladders looks in the future, and I might ask, whether or not it will exist at all for some people? 


    The make-up of households is one important factor, especially in the Rutland property market. The normal stereotypical married couple, 2 kids & dog of the 1970’s & 80’s has changed. Increasingly we have the need for larger houses where two families come together after divorce (plus kids), & need a property to house everyone, through to an increase in the number of one person households.

    Looking at the data for Rutland, of the 1,741 private rental properties in the Rutland County Council area, 34.69% are 1 person households. However, when we compare the number of 1 person Rutland households who have bought their own property with a mortgage, of the 10,556 owner occupied households in the area, only 5.77% are 1 person households. Compared to a decade ago, this explosion in demand for decent high quality rental properties that 1 person households require has not been met with an increase in supply of such properties. Increasingly I believe Rutland landlords need to consider this change in the make-up of Rutland households, as I see an opportunity here. Another interesting stat’ was that 13.84% of those 1,741 rental properties are lone parent households as well. Again, another opportunity for landlords!

    The government’s introduction in 2013 of the ‘Help to Buy Scheme’, where first time buyers only needed a 5% deposit, changed the perception of people’s ability to buy without having to save for a huge deposit. However, it might surprise you that 95% mortgages were re-introduced within 6 months of the ‘credit crunch’ in late 2009. So again, it comes down to people’s own perception. Many youngsters think they won’t get a mortgage, so don’t even bother trying.

    Coming back to the deposit, it is still a fact that once you start renting, it becomes much harder to save for a deposit, regardless of the size. Interestingly, 86% of the renters polled by the Halifax refuse to sacrifice the quality of accommodation they currently live in to reduce the amount of rent they pay in order to save for a deposit. This is the real reason why people aren’t buying – but renting. And, why demand for renting will continue to grow in the future (great news for landlords).

    Rutland tenants can upgrade the quality & size of the property they live in for a minimum rent increase. The average rent of a 2 bed property in Rutland is £525pcm, a 3 bed is £170 more at £695pcm, whilst the average 4 bed is £995pcm. If you had to make that jump when buying, the monthly mortgage payments would be stratospherically higher. Without any social pressure & with better quality rental properties compared to a decade ago, we will become a nation of renters within the next generation. The UK is becoming more like our European neighbours, where renting is ‘the norm’. Who is going to supply all these properties to rent? Landlords!
    Whether you are an existing landlord looking to grow your portfolio, or looking to become a ‘first time landlord’, my thoughts are to take advice from as many people as possible.

    As the majority of landlords buy their 'Buy-to-Let' properties in the same town as where they live, you might need specific advice about Rutland itself. 

    Please call me to arrange an appointment at either my Rutland or Stamford office and I will be happy to assist you.


    Friday, 14 August 2015

    Stamford Buy-To-Let; Demand and Supply

     
    Following on from my recent article about the state of the Stamford property market, and in particular, what had happened to the rents Stamford tenants have had to pay since the 'Credit Crunch'. If you recall, I said rents in Stamford are still 4.86% lower than they were in 2008. A Stamford landlord has since rung me after reading the Stamford Property Blog, wanting to know more of the story of what was happening to current rents in the town. The reason he asked was that his current agent hadn’t increased his rent for a number of years and was concerned if he was getting the best return from his buy-to-let investment.

    The Stamford rental market is all about supply and demand (isn’t it so in all parts of the economy?). On the supply side, 40 rental properties have come up for let in the last 31 days in Stamford. It sounds a lot until you consider there are 1,497 rental properties in Stamford, that means only 2.67% of the rental stock of properties in Stamford are coming onto the market each month (it is normally around 5%). One reason for this lack of new rental properties coming on the market is the fact that tenants seem to be staying in properties longer.
    With this lack of supply, newer tenants have to pay more to secure the property they want. And this is the crux of the matter ...properties they want. Older properties in Stamford that haven’t been maintained still retain their wood chip wallpaper from the 1970’s and thread bare carpets have seen their rents stagnate or drop. Tenants want either modern properties with all the 'mod cons' or older style properties that have been presented to an exceptional standard – and they are prepared to pay for the privilege. Rents for top quality properties in Stamford have risen by 0.4% in the last month. Any properties, old or modern, put on the market in good or excellent condition will rent in a matter of days.   
    Interestingly, looking at Stamford property values, the Land Registry have just released their latest set of data on property values. Throughout April 2015 (the latest set of data), property values rose in Stamford, with 1% growth, meaning they are now 4.3% higher than they were a year ago. When one looks at the regional picture, the East Midlands average property values rose by 1.4% in the last month. The difference doesn’t concern me, as the regional and local property values always even themselves out over the months.
    Looking forward, after considering all the statistics and talking to other property professionals, I expect property values in Stamford to rise by 3% to 5% over the coming 12 months, following the Conservative victory.  In a forthcoming article, I will discuss how the number of properties changing hands each month has dropped considerably in the last 10 to 15 years in the town.
    ...And so back to our landlord. Each property is unique and as his tenancy agreement allows him to inspect the property with notice to the tenant, we will be visiting the property next week. For more in depth thoughts and opinions like this on the Stamford Property market ... keep visiting the Stamford Property Blog.

    Friday, 7 August 2015

    Oakham Buy-To-Let; To extend or not extend...?

    Last week, a landlord from Oakham emailed me to ask, after reading the Oakham Property Blog, if he should extend his terraced house making an extra bedroom in the loft. He had a builder friend who owed him a favour, and thought a good way would be get an ‘inexpensive’ extension.

    Having more useable space is generally thought to be consistent with better quality accommodation and homeowners and tenants are prepared to pay for it. If you added a bedroom to a two bed terraced to make a three bed terraced, it will add 10% to the value of the property. Turn a three bed terraced into a four bed terraced and 9% will be added to the value. Looking at semi detached properties, turn a two into a three bed and 12% will be added to the value, whilst making a three bed semi into four bed will add 9% in value.


    However, before you rush off to the planning department there are some important considerations, whether you are a homeowner or landlord. What would be the cost of making that extra bedroom? The average value of a terraced house in Oakham is currently £196,300 whilst the average value of a semi detached house is £230,300, meaning to make money the cost of the extension would need to be less than £18,648 on the terraced property and £24,181 on the semi detached house. Talking to a number of trades people in the town, most are booking up into the New Year. Also, no matter how good a friend he was, I know of no builders that would charge as little as that. Maybe the builder was just thinking of a bit of pointing work on the chimney!
    Well, that got me thinking about how bedrooms affected rental prices and rent-ability as well. Interestingly below, you will see that whilst bedrooms do have an effect on the rent that can be achieved and the rent-ability of the property – the difference does not warrant the expense, hassle and trouble of extending.
    33.3% of the one bed properties on the market to rent in Oakham have a tenant with an average rent of £390 per month
    33.3% of the two bed properties on the market to rent in Oakham have a tenant with an average rent of £514 per month
    53.8% of the three bed properties on the market to rent in Oakham have a tenant with an average rent of £678 per month
    60% of the four bed properties on the market to rent in Oakham have a tenant with an average rent of £1,139 per month
     

    Now, if you want to increase the value of your property, be you an Oakham landlord or homeowner, there are things that cost a lot less than building extra bedrooms. Spruce up the exterior, emulsion all the rooms, install fresh carpets and curtains. For homeowners, a matter of a few hundred pounds will add thousands - whilst for landlords, these things can add an extra 10% to the rent that you can achieve.
     
    For more advice and opinion on the Oakham property market, please visit our Church Street office and keep visiting our blog for new updates.

    Friday, 31 July 2015

    Property Values rise by 0.2% in Stamford


    Property Values rise by 0.2% in Stamford

    Property values in Stamford rose by only 0.2% last quarter.  This follows several months of sluggish activity in the Stamford property market in the run up to the General Election, putting the average price of a property in Stamford at £274,100 - which is 3.8% higher than in March 2014.

    Interestingly, over the last few months the Council of Mortgage Lenders and estate agent trade bodies have reported seeing a fall in mortgage lending and enquiries from prospective homebuyers.  This is important because it comes amid an overall fall in housing market activity in Stamford.  Data from the Land Registry said completed house sales in Stamford in the 3 months to January 2015, (the most up to date figures available) fell by 13.22%, compared to the same 3 month period up to January 2014.

    However, I believe that the slowdown in the property sales in Stamford is supporting Stamford property values, as there is a shortage of houses coming onto the market.  Even though in the whole of the first quarter of 2015, Stamford property value increases may seem subdued when compared to 2014, let us remember, property values are still rising well above the level of inflation.

    As I have said many times before, the population in Stamford is growing at a much higher rate than the number of properties being built.  This increasing demand for a roof over people’s heads, which is outpacing the supply of new houses being built in Stamford, is creating a severe imbalance in the Stamford (in fact, in the whole of the UK’s) housing market.  Thus making home ownership an ever increasingly distant dream for many of Stamford’s potential 1st time buyers.

    In fact, I still maintain the view that house prices are likely to rise by around 3-5% in Stamford in 2015, ever taking into account this blip at the start of the year.  The reason being is that the rise reflects both strong economic conditions and steady market conditions with (and this is the most important factor) very low numbers of properties on the Stamford property market.

    Many Buy-to-Let landlords know that investing in the Stamford property market is a long-term strategy of 10, 20 or even 30 years.  Governments come and go, but unless South Kesteven District Council start to build hundreds of new properties per year to make up for the shocking lack of supply, Stamfordians will always want a roof over their head, and irrespective of whichever party is in power, if there aren’t any council houses and they can’t (or are unable to buy), a demand for rental properties will always remain strong.

    As my existing Stamford landlords will testify, (whether you manage your property yourself, or another local agent manages your property), everyone is always made to feel welcome when they pop in for a coffee to see us, to discuss anything to do with the Stamford property market such as how the town compares with its closest town rivals for example.  I don’t hard sell, I just give you my honest, straight talking opinion.  However, if you are too busy to pop into town, please just  keep visiting this blog for advice, intelligent commentary and analysis of the Stamford property market.

    Wednesday, 8 July 2015

    Super Semi-Detached in Stamford for Sale

    Essex Road, Stamford on for sale with a guide price of £124,950

    Excellent 3 bedroom mid terraced home, close to the town centre, schools, college etc., no upper chain, rear garden, spacious sitting room and my favourite feature...."ripe for renovation". 

    Spend a bit on this now and it will add value to your investment.  Be that as a family home or as long term buy to let.


     Contact Adrian McCarthy, UPP Property Agents on 01572 725 825 to arrange a viewing. 

    This is priced right and is an attractive proposition to all buyers.  My advice is this won't be on the market for long.

    Click on this link for full details:

    http://www.rightmove.co.uk/property-for-sale/property-35356773.html